

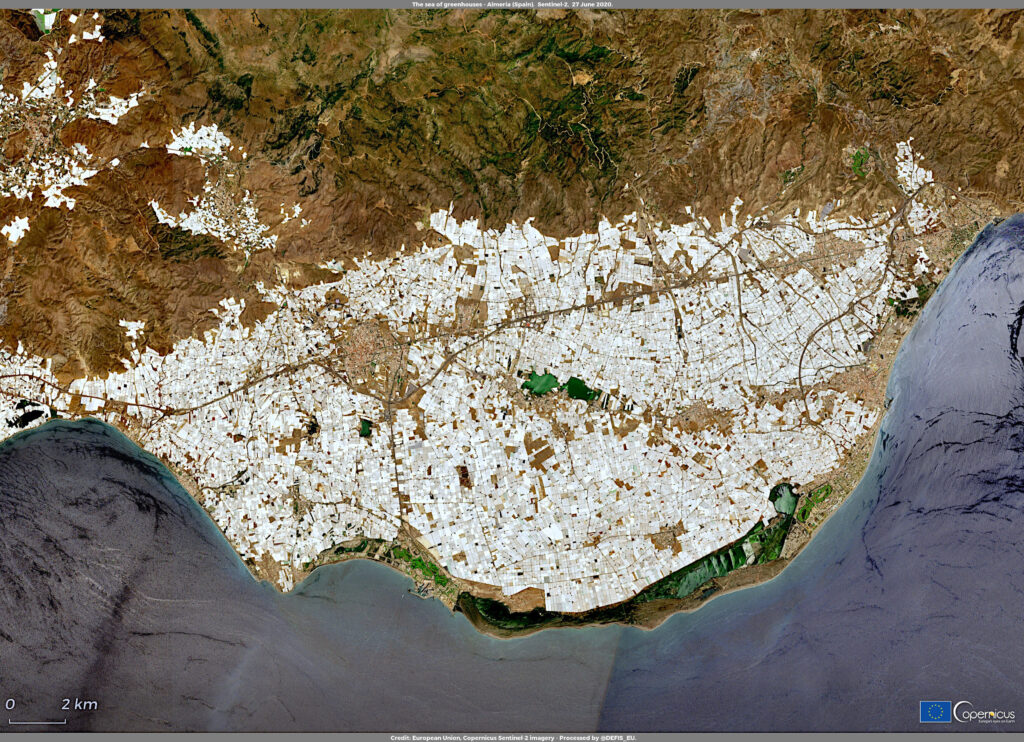
Spain’s tomato production in the 2025/26 season was about 2% lower despite a broadly stable cultivated area, according to Spanish fresh-produce federation FEPEX. The assessment formed part of a FEPEX account of the European Commission’s tomato market expert-group meeting held in Brussels on 15 October 2026.
FEPEX said the Spanish delegation, including its director Ignacio Antequera, pointed to several constraints on yields: a shift towards virus-resistant but less productive varieties, plant-health problems and adverse weather. The 2% figure describes the Spanish season, not tomato production across the European Union.
Higher costs are limiting the benefit of firmer prices
The association reported energy and transport costs around 16% above what the delegation described as normal conditions. It put the increase in plastics, containers and packaging at approximately 18% against that reference point. These figures are reported cost pressures, not measured year-on-year increases in an independently published input-cost index.
According to FEPEX, stronger tomato selling prices during the season have not produced a corresponding improvement in growers’ profitability. For protected-crop businesses, the combination matters because production decisions depend on both market prices and the costs of energy, crop protection, labour and packing—not on the headline selling price alone.
Moroccan competition remains a concern for cherry growers
FEPEX said the Spanish delegation also highlighted a loss of planted area in cherry tomatoes, particularly loose cherry varieties, which it linked to competition from Morocco and differences in labour costs and regulatory conditions. That is the federation’s assessment of the competitive pressure, rather than a finding that imports alone caused the acreage change.
Trade volumes discussed at the meeting put EU imports of fresh tomatoes from non-EU countries at 773,000 tonnes in 2025, including 527,000 tonnes from Morocco, FEPEX reported. On the other side of the market, the EU exported 383,000 tonnes to non-EU destinations, of which 279,000 tonnes went to the United Kingdom. These are historical 2025 trade totals, not volumes shipped in October 2026.
Representatives from Belgium, the Netherlands and Poland raised their own concerns about weather, the tomato brown rugose fruit virus and energy costs, according to the FEPEX meeting account. The discussion therefore extended beyond Spain, but the Spanish production estimate cannot be extrapolated to every EU growing region.
What operators should watch next
For greenhouse growers and buyers, the practical questions are whether prices will compensate for production and packaging costs, how plant-health pressures affect marketable yields, and whether the mix of domestic and imported tomatoes changes in the next season. FEPEX’s briefing is a participant’s view of a market discussion; it does not announce new EU trade rules or establish a settled forecast for the 2026/27 crop.
Key takeaways
- FEPEX estimates Spain’s 2025/26 tomato production fell about 2%, despite broadly stable cultivated area.
- Spanish delegates reported energy and transport costs around 16% above normal conditions, and plastics and packaging around 18% higher.
- FEPEX reported 773,000 tonnes of EU fresh-tomato imports from non-EU suppliers in 2025, including 527,000 tonnes from Morocco; margins remain the main concern for growers.